

It’s been a quiet few weeks of focused work on other projects for me, so the ‘Stack has sat back burner. It’s just as well, as things have otherwise been pretty boring and quiet on the Bitcoin front. The bears have been enjoying a long season — both in the BTC market and in our local Colorado towns — but with cooler mornings and deepening macro signs, at least some of the bears may have started going into hibernation.
The Bitcoin bears enjoyed many weeks of frolic in the summer market malaise until BTC took a +24% price rip starting August 18. Many bears got their faces ripped off with more than $6.5 billion in bitcoin shorts getting wiped out in August. With such a violent move upward, the question over the weekend was whether it would stick this week. So far, the answer seems to be yes, with BTC holding around $79,000 at this writing.
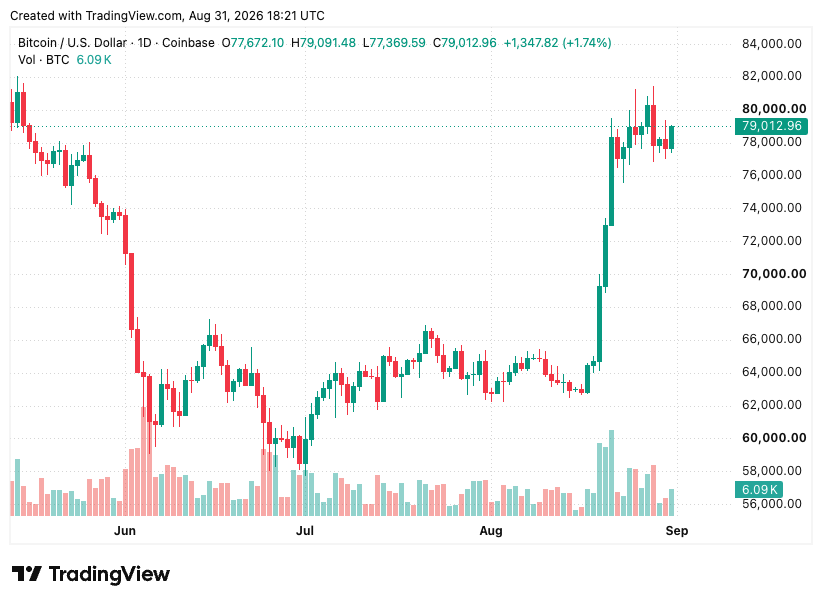
BTC is off about 5% from last week’s ~$81.4K high, with August closing bitcoin’s best monthly gain since the wild 2017 cycle. As a “Class of 2017” inductee, that makes it the biggest one-month rally I’ve witnessed.
I’m not doing victory laps yet, and the bears may have their day yet. When you zoom out for the past 12 months, bitcoin is still down almost 28% from this time last year. Collectors of shiny rocks still have more to celebrate than us humble corn collectors.
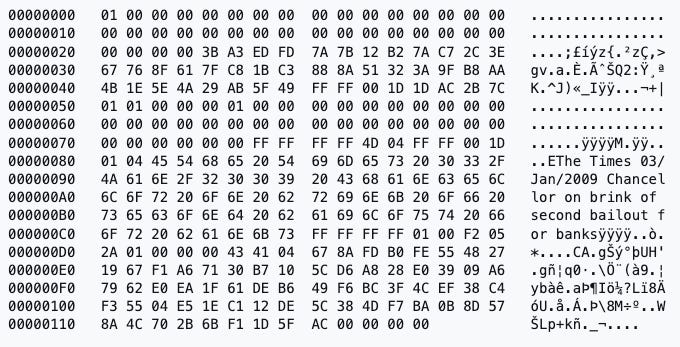
The bigger point is that bitcoin’s August rally happened when nothing dramatic was happening in bitcoin. BTC moved in line with macro news, in keeping with the hard money narrative encoded in the Genesis block.
Never fix today what you can put off until tomorrow… Or forever.
On August 18, U.S. public debt crossed $40 trillion. Whether this milestone was merely coincidental or whether it triggered a reaction we can only speculate but the following day, Treasury Secretary Scott Bessent made an unscheduled announcement that Treasury would double its long-end bond buybacks — from $2 billion to at least $4 billion per operation in the 10-to-30-year part of the curve. Lyn Alden’s subscriber report this week does a good job explaining what that means, so I’ll borrow from her (and I encourage you subscribe to her feed).
When Treasury retires long-dated bonds by issuing more short-dated Treasury bills instead of raising the size of regular bond auctions, they shorten the average duration of the national debt. This increases liquidity in the system.
For a mental exercise, consider the national debt as an enormous mortgage. (Suspend for a moment the question of whether it’s a mortgage for a home you’d actually buy and want to raise your family in. Let’s also pretend that both the principal and the interest don’t continue to grow every month.) Buying back long-duration bonds and funding it with short-term bills is like refinancing from a fixed 30-year mortgage into an adjustable-rate loan to make the monthly payment smaller today. It works until short-term rates move up. At that point, the bill comes due faster and larger.
This is effectively what Treasury is doing: refinancing America’s mortgage from a 30-year into an ARM to make the monthly payment hurt less. It’s an effort to give the Trump administration cover by letting them say “we lowered debt payments” in a midterm election year and count on future inflation to burn off debt, in the hopes that American voters won’t understand the difference. (In fairness, most American voters probably indeed won’t understand the difference.)
Two things make this interesting. The first is Bessent’s blatant hypocrisy. In 2024 he criticized then-Secretary Janet Yellen for doing exactly the same thing on a smaller scale. In his words, the Treasury Secretary was “distorting Treasury markets” by putting a “thumb on the scale” exposed the government to refinancing risks, and papered over the gravity of the nation’s financial health. He is now doing the same thing on a much larger scale.1
Stanley Druckenmiller — Bessent’s former boss from their Soros days — published a Wall Street Journal op-ed on August 24 calling the unscheduled, bill-financed buybacks, months before a midterm election, an unnecessary and optically terrible intervention.2 Druck argued that if Washington doesn’t like the level of yields, the “honest” fix is for Congress to cut the deficit.
The second point Lyn makes is that Bessent announced this when nothing was broken. This isn’t the March 2020 COVID collapse or the 2022 UK gilt crisis. Long-end yields are a little above 5%. This is roughly a 20-year high, but it doesn’t seem to be an unreasonable price to pay someone to lend you money for thirty years. Treasury is intervening because they don’t like the level of the long yields, so it’s leaning on them with short-term financing.
Alden points out that U.S. debt-to-GDP is over 100%, and annual interest expense is now running about $1.25 trillion — larger than the entire U.S. military budget. At these levels, deficits stop being about discrete policy choices and become a structural reality politicians have to manage. Rather than tighten the belt and go on an aggressive spending diet — and who wants to do that in an election year? — Congress will just let Dr. Bessent prescribe the fiscal equivalent of a bariatric band so we can continue to gorge on debt, postponing the inevitable, if delayed recompense for our gluttony. (Cue Mr. Creosote.)
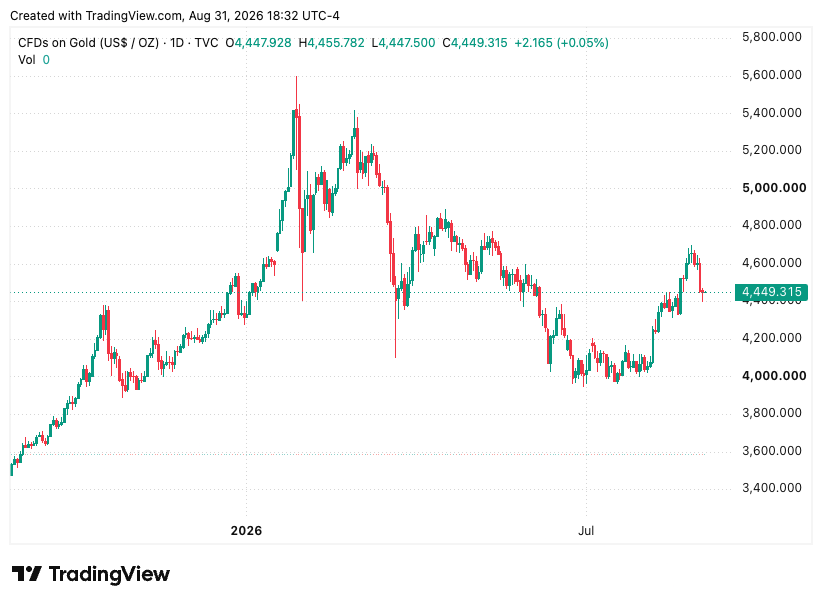
It’s no coincidence that bitcoin’s meteoric August rally started with Bessent’s announcement. The market rewarded bitcoin not as a speculative risk opportunity, but as a bid for a resilient, scarce asset. As the dollar sold off beginning on August 19, bitcoin ignited a run from $64K to $80K. Gold climbed from $4.3K to $4.6K.
As I wrote previously, and as anyone who has studied Bitcoin at all understands, bitcoin is not just provably, undeniably scarce. It is fixed and finite and its issuance rate decays over time, making it increasingly scarce into the future. To the extent there is a large enough audience of people who believe that value is found in scarcity — and to the extent the “Y-axis” is measured by infinite dollar — that which is scarce will always trend up and right against a decaying dollar. Bessent just further exacerbated the decay of bitcoin’s most popular Y-axis.
Optimizing for resilience
This is not investment advice, but its truth should be readily apparent: anything that is broadly desirable and inherently scarce will always trend upwards against anything else that is less scarce. This has generally tended to be true with gold, bitcoin, real estate, art & other collectibles, and my personal affinity, classic German cars. When currencies debase, those with spare currency seek to store value in things that will at least hold value against a decaying Y-axis.
It’s also important to understand the arbitrage opportunities among different Y-axes. As I’ve learned from my colleagues, I’ve come to acutely appreciate how various currencies hold or lose value against other currencies. Of course, the Forex world has known this forever, but that isn’t the world I come from. I come from a non-financial (legal) background and have the perspective of being an American man who grew up in America during a long run of American dollar dominance. Only when I came to lead our company did I come to appreciate how policy decisions would so profoundly impact the value of the dollar compared to other fiat currencies. Since then I have learned first-hand the value of genuine jurisdictional diversification: getting exposure to income-generating resources in countries like Switzerland and Singapore, to name just two examples.
As my friend Jacob Shapiro so clearly articulates, the U.S. is no longer the sole global hegemon. We are undeniably — irreversibly — in a multipolar world. It is then suboptimal for any affluent person to have 100% of their total wealth denominated in a currency whose Treasury Secretary has reaffirmed in no uncertain terms that the dollars you hold today will be worth less than the dollars you hold tomorrow.
I’m no investment wiz and I wasn’t a math major. But in my book, I have a simple heuristic:
Scarce assets > abundant fiat.
Abundant fiat > infinite fiat.
Ergo, scarce assets > infinite fiat.
None of this should be interpreted to be a “market call” on bitcoin or anything else. (Though I do condone buying classic German cars.) This is just how I personally think about building for resilience. I’m not a financial advisor, and this isn’t investment advice. But it would be inauthentic to pretend to just be a neutral observer of a continuing debasement trend I clearly have views about. The whole point of building for resilience rather than trying to predict market behavior is to not try to be right about the future. It’s to try to be okay across several versions of a future that is unpredictable and over which I have no control. That’s a philosophy, not a trade.

Checking in with Check
James Check (Checkmatey) puts out consistently great analysis. He’s someone I read every week, and today’s piece titled “The Bears’ Last Stand” posits $82K as the last line the bears can defensibly hold. If bitcoin closes this week above that line, it will clear both the May high and bitcoin’s 50-week moving average at the same time. His lips to God’s ears, but it feels like we’re within shouting distance.
Of course anything can happen between now and then, but James’s analysis describes a healthy recovering market. Long-term holders aren’t selling into the rally. Buyers who accumulated through the last several weeks pain are sitting still. Futures funding is quiet and open interest fell as bitcoin’s price rose, making the action seem more like value buying rather than gamblers pushing each other uphill on borrowed money. Some short-term holders took profit at $81K, and spot demand absorbed it. Spot ETFs pulled in nearly $3 billion over the past two weeks.
Michael “giga-bull” Saylor’s Strategy started buying again. Making their first purchase since June, MSTR bought 4,603 BTC for ~$370 million. This was the first time in almost three months during which Strategy sold bitcoin (at a juicy loss) to fund its preferred-stock dividends. I remain skeptical of Strategy’s strategy of funding coupon payments with a non-yielding asset. But according to their August 31, 2026 form 8-K, MSTR’s average basis in their BTC stack is $75,412, finally putting them back into an unrealized gain position after months of selling underwater. If bitcoin holds its gains, the “Saylor as forced seller” dread that loomed over the whole summer will abate. MSTR stepping back in at scale helps affirm the demand suggested by the ETF data. We’re only two weeks into the market reversal but bitcoin’s recent break to the upside is a welcome change from the insufferable grind of the summer doldrums.
As I get ready to present continuing education sessions about bitcoin and wealth structuring, I’m reminded that when I started building the first presentations in 2018 to help estate planners and tax professionals understand how to design wealth strategies with bitcoin, BTC’s price was a little over $6,000. Shortly after I started delivering those presentations, the price fell below $4,000. In preparing to hit the circuit again it’s worth reflecting that in only 8 short years bitcoin’s USD price has increased by well over 10X.
Two other things flying under the radar
It’s easy to get enthusiastic about bitcoin’s spot price, but a couple of other bitcoin-related things are worth spilling a little digital ink.
On August 25 the SEC sent a proposed crypto-custody rule to the White House for review. It would define what counts as a “qualified custodian” for investment advisers and funds. The text of the rule is unpublished during the initial review process but publication is expected by October, followed by a 60-day comment window.
One of the things I harp on to bitcoiners who hold generational wealth in bitcoin is that blind adherence to the “not your keys, not your coins” mantra is not only a vestige of a time when bitcoin was only peer-to-peer electronic cash, it also creates a unilateral point of catastrophic failure when the bitcoiner becomes incapacitated or dies and seeks to transfer that bitcoin wealth to heirs. Counting on untested miniscript dead-man’s switches or relying on friends to recover and properly use distributed key shards is a fool’s game. When wealth is consequential and the cost of “getting it wrong” is unacceptable, Bitcoiners have to level up their key management strategy. And when the level of wealth is such that the Bitcoiner wants “fiat-world” outcomes — legally recognized asset protection, tax mitigation, enforceable inheritance guardrails, bitcoin sitting side-by-side in a coordinated wealth operating system — the Bitcoiner must adapt fiat-world solutions to get those outcomes. This means legally-recognized, title-held, fiduciary-controlled strategies.
This is not a paean to qualified custody. As a bitcoin veteran of nearly a decade, I deeply value the idea of maintaining key sovereignty. But as I’ve witnessed bitcoin dramatically increase in value against the dollar, I’ve come to appreciate that the solution that was effective to manage the digital “cash in my pocket” is no longer adequate to manage an asset that has proven to store consequential value. As a career estate planner, I also appreciate that the world we live in is governed by laws. To the extent I want the benefits and protection of those laws (and I do), I must upgrade my definition of sovereignty from “unilateral control over private key material” to “orchestration of systems I control.”
Qualified custody shifts the locus of risk; it doesn’t eliminate it. Transferring bitcoin to a regulated custodian doesn’t make the risk go away. It shifts the risk from a single individual (who ages, becomes forgetful, makes dumb decisions, has imperfect systems) to an institution with audited controls, insurance, regulatory oversight, and legal recourse.
The Bitcoiner who designs and activates a comprehensive system to manage wealth does not surrender control by transferring tokens to a qualified custodian. To the contrary; they are taking control over the totality of their situation and shifting the risk of loss to where it can be more readily recovered, if necessary.3
A federal rule defining the type of institution that will “qualify” as a qualified custodian is a much bigger deal in the long run than any single month’s return.
Here’s some shocking news: on the Congressional front, nothing happened. The “CLARITY” Act is still up for cloture vote on September 15 and it still needs ± seven Dems to cross the aisle. Opinions about the substance and merits of the Act are certainly mixed within the bitcoin and broader crypto communities. Whether the Act makes progress over the next few weeks will remain to be seen. Several senators are holding out for conflict of interest safeguards to be added before supporting the legislation. And in a midterm year already hotly contested…
What to watch
$82,000. Will bitcoin hold its two week gains? If so, will it be the bears’ last stand?
Whether demand persists. Two strong ETF inflow weeks, and Saylor’s back at the buying window. But nine-days of inflows ended August 28 with an outflow. Will the bid carry into September, or was August just a blip?
September 9. That’s when Bessent’s increased bond buybacks take effect.
September 15 and 16. CLARITY’s cloture vote, then the FOMC the next day with live hike risk under Warsh. Two policy events back to back into a market that just rallied into the headwind.
For the past few weeks I’ve been working on a continuing education presentation on “Jurisdiction, Rule of Man v. Rule of Law, and Planning for Resilience… blah blah blah” that I’ll be presenting at a few spots in the U.S. The point I want to make here is not that Bessent is a unique hypocrite. The point is that hypocrisy is not in the least unique to politicians, but it is simply part of the acrid death stench of “rule of man.” This merely marks another stop along the chain of governance-by-whoever’s-in-charge, rather than the feckless American Congress actually doing its job. The specific strategy Bessent attacked as fiscally irresponsible when Dems ran the Treasury is now the tactic he’s deploying on a larger scale from the same chair. This is not a partisan point — the pattern is the point, and it runs through both parties with nauseating predictability. The policy didn’t change; just the name on the door.
Druckenmiller used AI to write his op-ed, a move he defended (and WSJ backed). In fairness and full disclosure, I have Claude get me started with a lot of my work including most of my analysis that goes into this Substack. But in the end I own every word I publish — for good and for ill.
And bonus points for the affluent Bitcoiner who not only structures intelligently using properly designed & managed trusts or other entities + qualified custody, but also diversifies jurisdiction risk!